
Fort Lauderdale’s home-buying process follows Florida law and Broward County norms that differ from most other states. The contract gives buyers a cancellation right that most states do not offer. The closing costs include a state tax that surprises nearly every out-of-state buyer. And the waterfront and flood zone disclosures add due diligence that most inland markets don’t require.
This guide covers every step with emphasis on what is specific to Fort Lauderdale. If you are relocating or buying here for the first time, the sections below prepare you for what is coming.
What Sets the Fort Lauderdale Market Apart?
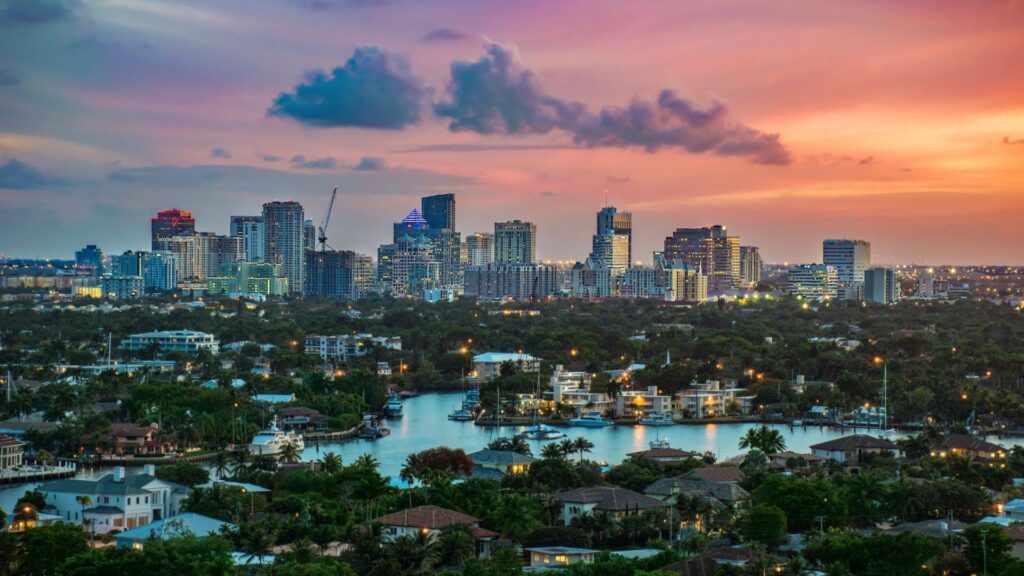
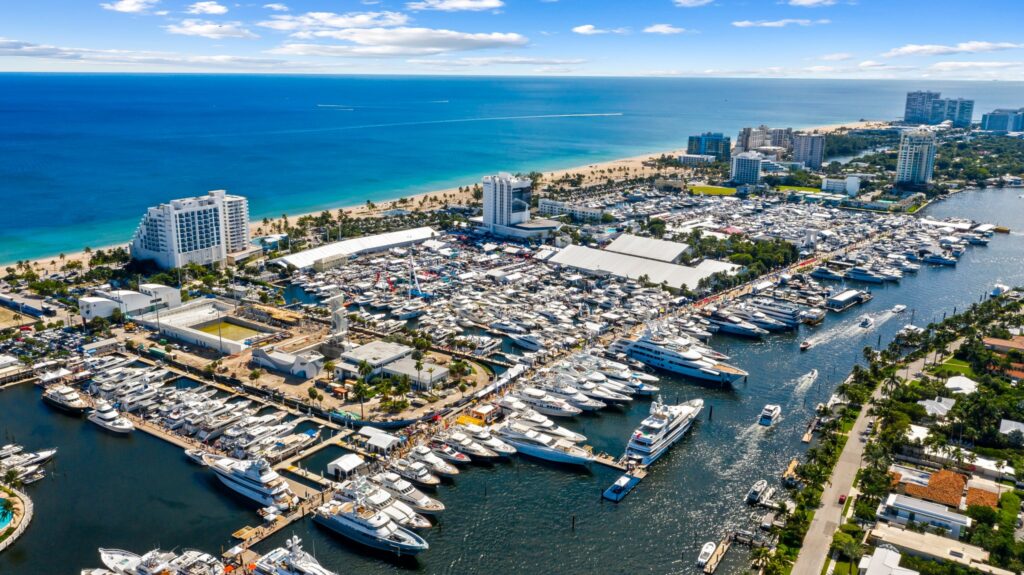
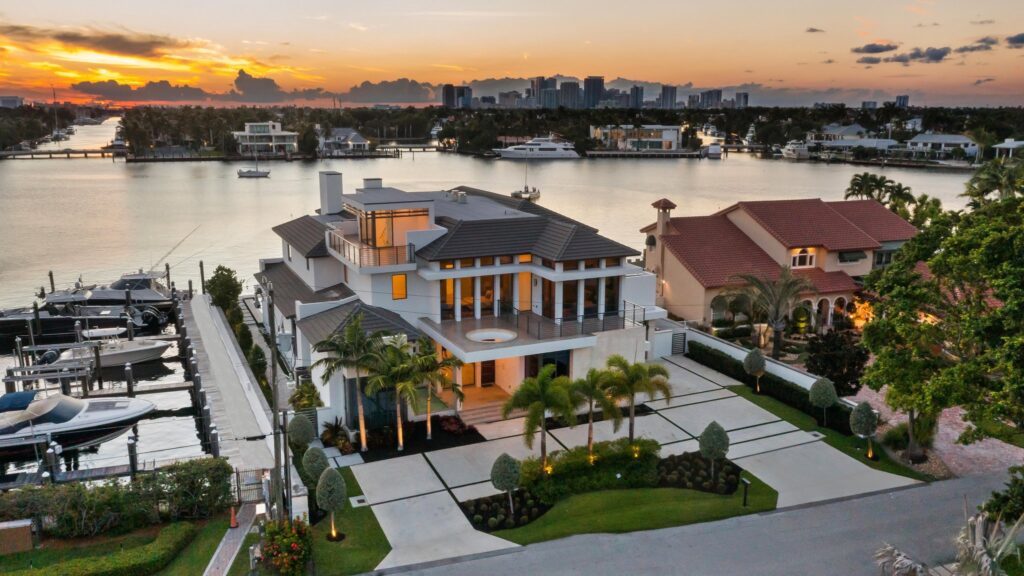
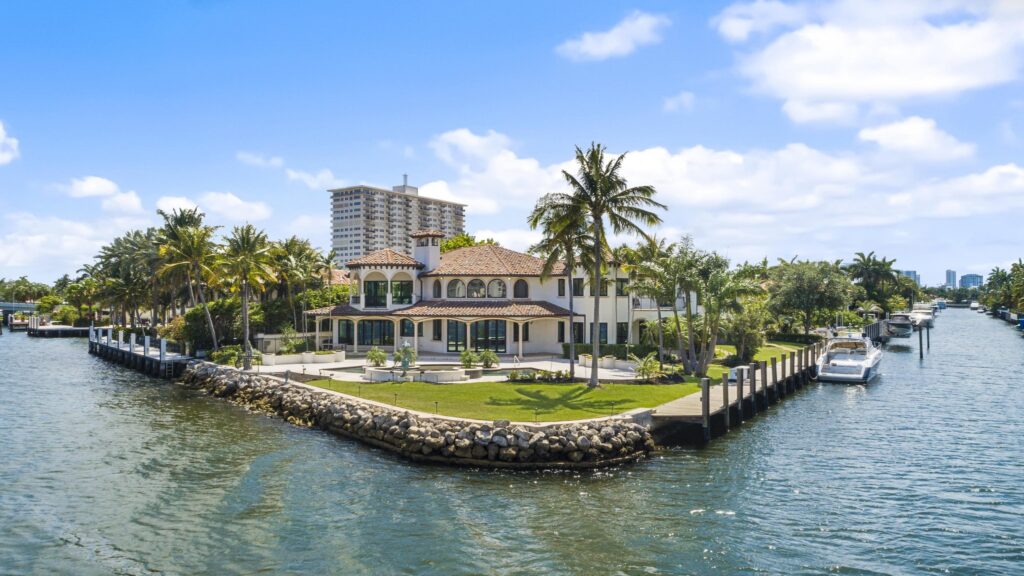
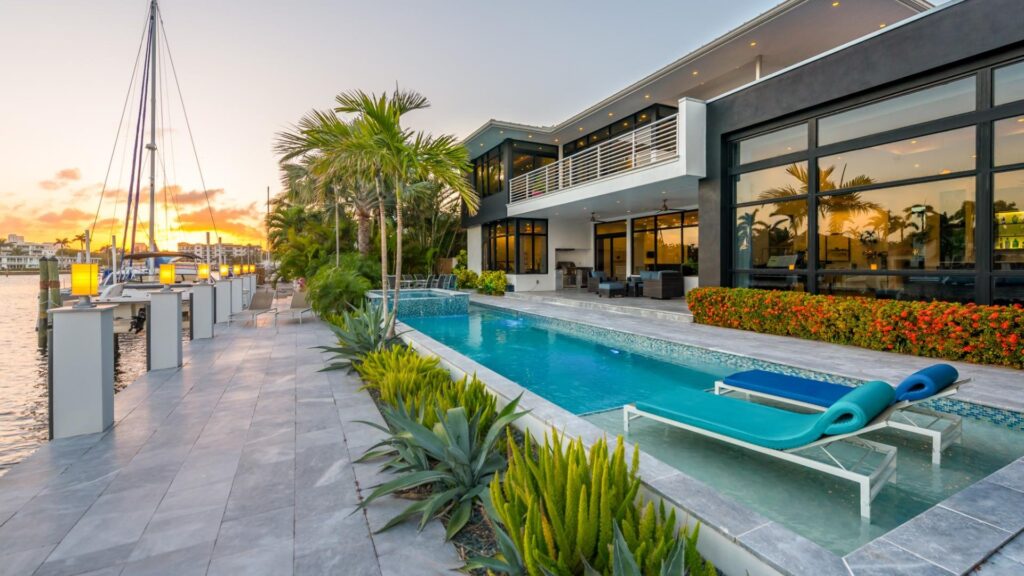
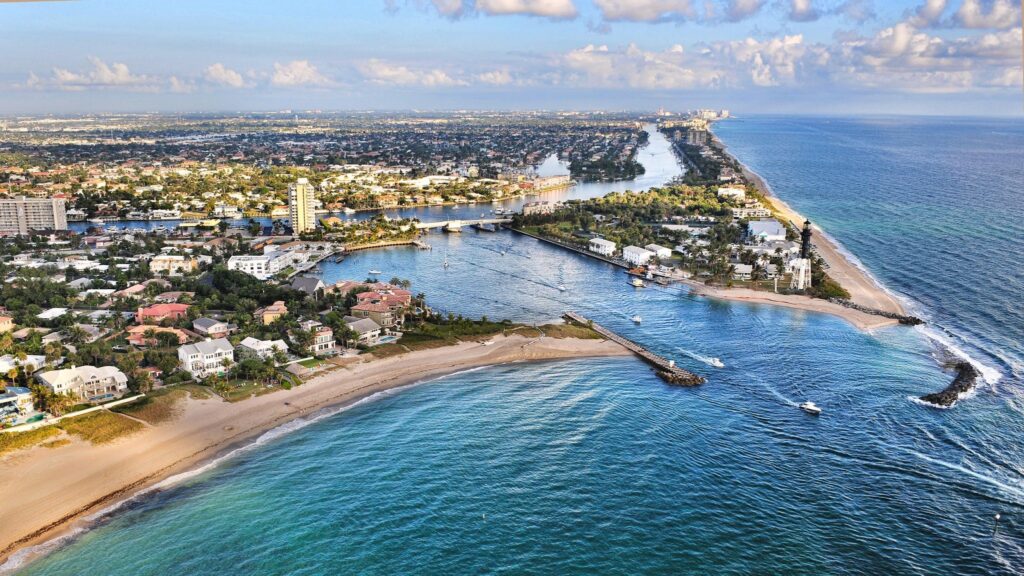
Fort Lauderdale has 165 miles of navigable waterways, more per capita than any other U.S. city except Venice, Italy. That waterfront inventory in the $900K to $5M range is the market’s defining feature and its primary price driver.
Broward County’s median home price reached $620,000 in Q1 2026, up from $390,000 in 2021 — roughly 59% appreciation over five years (Florida Realtors Q1 2026 Market Report).
Single-family homes in Fort Lauderdale’s canal neighborhoods — Las Olas Isles, Rio Vista, Coral Ridge — start at $1.2 million for waterfront access and reach $8 million or more for deepwater lots.
The Dotoli Group has closed over $1 billion in Fort Lauderdale residential sales since 2013, ranked #1 Fort Lauderdale Large Team and #22 in Florida by volume (RealTrends Verified 2026).
One recent client: “Josh, Megan, and the entire Dotoli team delivered on every single promise they made and, in less than 60 days, sold our house over asking price.”
How Much Do You Need to Buy in Fort Lauderdale?
Two numbers matter: the down payment your loan type requires and the Florida-specific closing taxes most buyers have never paid before.
Loan Limits and Down Payment
Any loan above $766,550 in Broward County in 2026 is a jumbo loan (Federal Housing Finance Agency), which requires 10% to 20% down and stronger reserve requirements. Most Fort Lauderdale single-family purchases in the $900K to $2.5M range involve jumbo financing or cash.
Florida Documentary Stamp Tax
Florida charges $0.70 per $100 of the purchase price on the deed and $0.35 per $100 of the loan amount on the mortgage note (Florida Department of Revenue).
On a $1.5 million purchase with a $1 million mortgage, that is $10,500 on the deed plus $3,500 on the note — a Florida-specific cost that buyers from most other states have never encountered.
Every cost layer beyond the mortgage is detailed in the hidden costs of buying a home in Fort Lauderdale.
How Does the Florida As-Is Contract Work?
Florida’s standard purchase agreement is the FAR/BAR As-Is Residential Contract. The buyer has a 15-day inspection period during which they can cancel for any reason and receive a full refund of the deposit.
No defect needs to be cited. If the buyer notifies the seller in writing before the period expires, the seller returns the deposit.
This means the inspection period is the leverage, not the defect list. Book every inspection on Day 1 or Day 2.
For a waterfront property, schedule both a general home inspector and a licensed marine contractor the same day the period opens. Waiting until Day 8 or 10 leaves no room for renegotiation before the window closes.
The complete waterfront inspection checklist is in Buying a Waterfront Home in Fort Lauderdale: What to Know.
Step-by-Step: Buying a Home in Fort Lauderdale
Step 1: Get full pre-approval before making any offer
Pre-qualification is a soft estimate based on self-reported data. Sellers in the $900K to $3M range will not accept offers backed by a pre-qualification letter.
Get a verified lender pre-approval with documented income, assets, and credit. For jumbo purchases, add a proof-of-funds letter from your financial institution.
Step 2: Choose a neighborhood before you start touring
Fort Lauderdale’s neighborhoods have different canal depths, bridge clearances, school zones, and commute profiles. Coral Ridge offers mid-canal inventory with solid access to Bayview Drive.
Victoria Park is walkable to Las Olas. Harbor Beach has gated access and some of the deepest canal frontage in the city. Picking the right neighborhood before touring removes weeks of wasted showings.
Step 3: Work with an agent who has closed in that neighborhood recently
The Dotoli Group has transacted across all of Fort Lauderdale’s major waterfront neighborhoods, with featured listings ranging from $849,000 to $6,995,000.
That transaction history shows which lots have active dock permit issues, which seawalls are nearing the end of life, and what a realistic offer looks like on a property that has been sitting for 60 days.
Step 4: Price your offer on closed comparables, not list price
Well-priced inventory in Fort Lauderdale’s mid-to-upper range doesn’t sit. Buyers who open low, hoping to negotiate up, typically lose to buyers who price the first time correctly.
The past 90 days of closed comparable sales in the specific neighborhood are the only number that matters.
Step 5: Use every day of the inspection period.
Book all inspections on Day 1: a general home inspection, a seawall inspection (if waterfront), a roof certification, a wind mitigation report, and a mold and termite inspection if indicated.
Total cost ranges from $800 to $2,500, depending on property type. This Fort Lauderdale home inspection guide covers which add-ons are worth the cost in this market.
Step 6: Close with a title company, not an attorney
Florida is a title-company state. A title company handles closing, prepares the closing disclosure, holds escrow, and issues title insurance.
This differs from many northeastern and midwestern states where attorney closings are standard. You do not need a real estate attorney unless the transaction has unusual legal complexity.
What Are Fort Lauderdale Closing Costs?
Buyers in Fort Lauderdale pay 2% to 4% of the purchase price in closing costs. On a $1.5 million purchase, that is $30,000 to $60,000 beyond the down payment.
The items that most consistently catch out-of-state buyers:
- Documentary stamp tax on the deed: $0.70 per $100 of purchase price
- Documentary stamp tax on the mortgage note: $0.35 per $100 of loan amount
- Intangible tax on the mortgage: $0.002 per $1 of loan amount (Florida Dept. of Revenue)
- Owner’s title insurance: Florida promulgated rate of approximately $5.75 per $1,000 on the first $100K, $5.00 per $1,000 thereafter
- Prepaid items: first year homeowner’s insurance, prepaid interest, and initial escrow for taxes and insurance
In Broward County, sellers typically pay the owner’s title insurance premium. In Miami-Dade, buyers typically pay. Know the local custom before you negotiate a credit.
Year-one and year-two property tax projections by price point are based on property taxes on a Fort Lauderdale single-family home.
The Florida Homestead Exemption: What Buyers Must Know
Florida’s homestead exemption reduces your taxable assessed value by $50,000 if the property is your primary residence—a $1,000 annual tax savings at Broward County’s 20-mill rate.
The Save Our Homes provision then caps annual increases in assessed value at 3% or the inflation rate, whichever is lower (Florida Department of Revenue).
The application deadline is March 1 of the year following your purchase. If you close in October 2026 and miss the March 1, 2027 deadline, you forfeit that year’s exemption with no appeal option. Apply through the Broward County Property Appraiser at bcpa.net. Put the closing date on your calendar.
Flood Zones in Fort Lauderdale: What Buyers Must Check
FEMA’s Risk Rating 2.0 methodology, rolled out in 2021 and 2022, recalculated flood insurance premiums for properties nationwide (FEMA Risk Rating 2.0). Many Fort Lauderdale properties that carried low premiums under the prior system saw increases. The current owner’s premium is not a reliable indicator of what you will pay.
Florida law requires sellers to disclose flood zone designation. Before removing contingencies:
- Pull the property’s flood zone at msc.fema.gov
- Request the elevation certificate from the seller
- Get an independent flood insurance quote from a broker who writes both NFIP and private policies.
- Ask for the property’s claims history; prior flood claims attach to the property, not the owner.
Properties in Zone AE with a finished floor well above the base flood elevation often carry lower premiums than Zone X properties that were repriced upward under Risk Rating 2.0.
Common Mistakes Fort Lauderdale Buyers Make
Treating pre-qualification as pre-approval. Sellers in this price range will not accept pre-qualification letters. Get full lender verification before your first offer.
Underestimating total ownership cost. Annual ownership costs above $1 million in Fort Lauderdale typically run $60,000 to $140,000 beyond the mortgage, including property taxes, homeowner’s insurance, flood insurance, HOA (where applicable), and maintenance.
Skipping the seawall inspection. A general home inspector is not licensed to assess seawall structural integrity in Florida.
Full seawall replacement in Broward County runs $60,000 to $90,000 for a standard residential lot. Buyers often discover this cost after closing because they didn’t know to request a marine contractor inspection.
Missing the homestead exemption deadline. March 1. No exceptions, no retroactive filing.
Choosing an agent without closed deals in that neighborhood. Fort Lauderdale’s waterfront market has micro-dynamics that vary by canal, street, and dock permit history.
Looking To Buy/Sell?
The Dotoli Group has closed over $1 billion in Fort Lauderdale residential sales since 2013, ranked #1 Fort Lauderdale Large Team and #22 in Florida by volume (RealTrends Verified 2026).
If you are targeting a specific neighborhood, planning a relocation, or evaluating a property you found on the MLS, the Dotoli Group handles Fort Lauderdale’s waterfront and single-family market at every price point.
Talk to the Dotoli Group — call or message directly to get a neighborhood-level analysis of your target area.