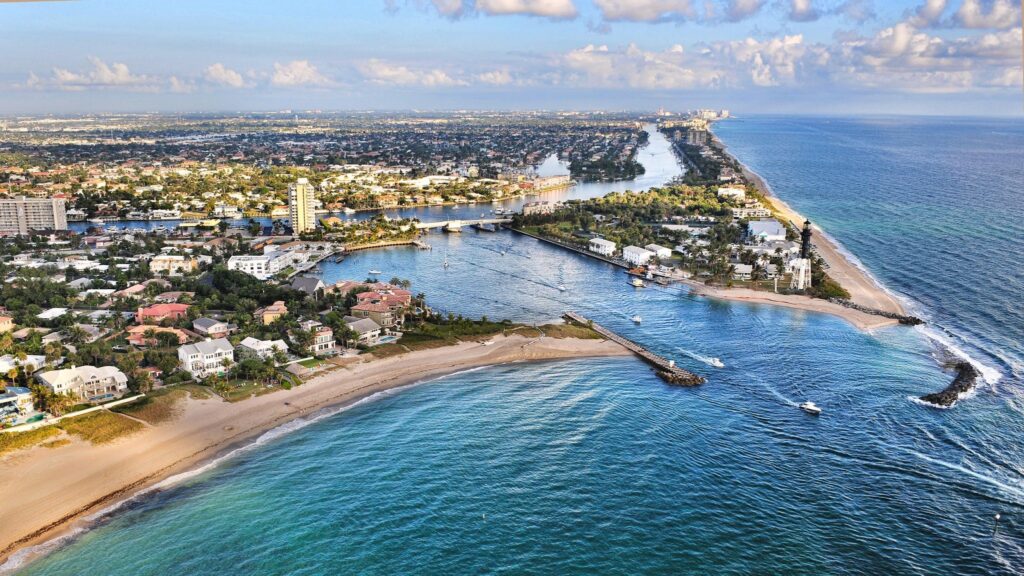

Fort Lauderdale receives an average of 61.9 inches of rainfall annually, with the majority of it falling between May and October during the wet season that overlaps with Atlantic hurricane season (NOAA Climate Data Online).
For buyers evaluating a purchase in Fort Lauderdale, that climate profile is not a background detail. It directly determines insurance costs, flood zone designation, required building features, and the long-term value trajectory of waterfront properties.
Buyers who understand the weather data before making an offer negotiate differently and budget more accurately than those who encounter it at closing.
Does Hurricane Season Affect When to Buy in Fort Lauderdale?
Atlantic hurricane season runs from June 1 through November 30, with peak activity between mid-August and mid-October (NOAA National Hurricane Center).
During this window, some sellers price more aggressively to close before season peaks, and inventory sometimes sits longer because out-of-state buyers delay travel.
For local buyers or buyers who have already committed to Fort Lauderdale, hurricane season can present negotiating advantages that the spring market does not.
The practical impact on a purchase is less about timing and more about preparation. Before any Fort Lauderdale offer goes in, buyers should verify the property’s flood zone designation, request the elevation certificate, and obtain an insurance quote.
These three steps take longer during active storm seasons when insurance underwriters slow processing. Building them into the due diligence timeline before you need them is the right approach regardless of when you buy.
Broward County has received direct and indirect hurricane impacts in 10 of the past 25 years. Buyers treating hurricane risk as a hypothetical are not reading the historical record accurately.
How Do Flood Zones Affect Fort Lauderdale Home Purchases?
FEMA designates flood zones across Fort Lauderdale ranging from Zone X (minimal flood hazard) to Zone AE and VE (high hazard, base flood elevations established).
Most waterfront properties, including canal-front homes, Intracoastal properties, and oceanfront parcels, fall in AE or VE designations.
Properties with federally backed mortgages in these zones require flood insurance as a condition of closing (FEMA Flood Map Service Center).
The flood zone designation affects three parts of a Fort Lauderdale purchase. First, it determines whether flood insurance is mandatory.
Second, the base flood elevation on the elevation certificate determines the annual premium.
Third, it affects future insurability and resale. A property with a poor elevation rating relative to its base flood elevation is harder to insure affordably and harder to sell to buyers with conventional financing.
Buyers should request the elevation certificate from every waterfront seller and review it with an insurance broker before the inspection period closes.
Zone VE applies to Fort Lauderdale’s direct oceanfront corridor and carries the highest NFIP rates because it accounts for wave action in addition to flood depth.
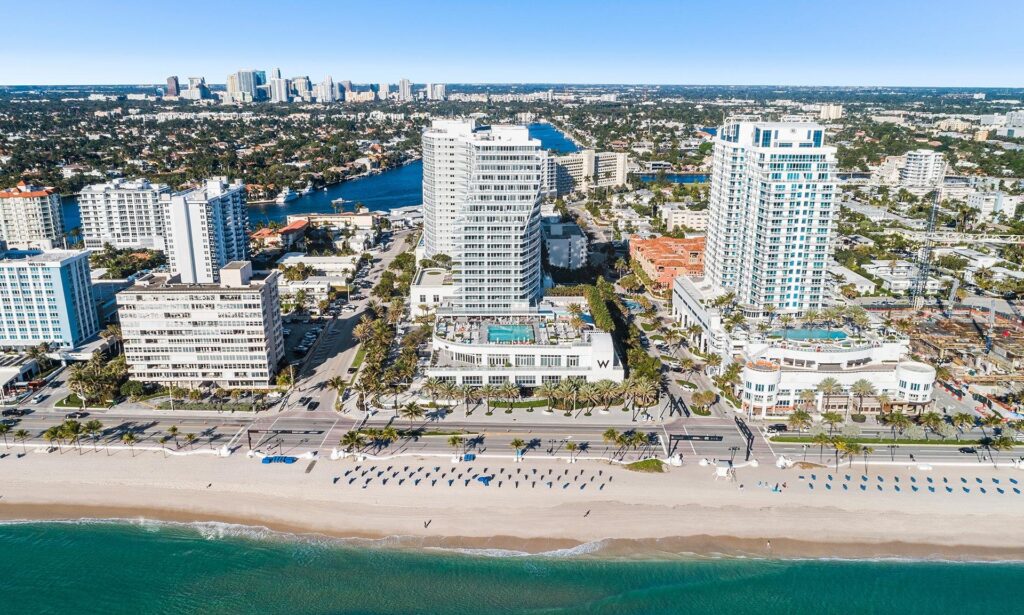
Harbor Beach, A1A properties, and barrier island homes typically fall within VE or AE zones, which have the most restrictive elevation requirements.
What Does Fort Lauderdale’s Rainfall Mean for Home Buyers?
Fort Lauderdale’s 61.9-inch annual rainfall average is roughly double the U.S. national average of 30.5 inches. That volume, concentrated in a six-month wet season, puts sustained pressure on drainage systems, roofing, exterior paint, landscaping, and foundation waterproofing.
Buyers evaluating older properties should treat deferred maintenance items related to water intrusion as higher-priority items than they would in a drier climate.
The wet season also concentrates property inspection findings. A home inspection conducted in May through September will surface moisture-related issues, drainage patterns, and roof performance under load conditions that a January inspection may not reveal. Buyers who can schedule inspections after heavy rain events get more informative reports.
Fort Lauderdale’s stormwater infrastructure has been significantly upgraded in recent years, but neighborhoods in the city’s lower-lying western areas still experience standing water after heavy events.
Buyers evaluating properties in those areas should research the specific parcel’s drainage history, not just the neighborhood’s general reputation.
How Does Sea-Level Rise Affect Fort Lauderdale Property Values Long-Term?
NOAA’s Fort Lauderdale tide gauge at the Port Everglades entrance shows a sea-level rise trend of approximately 3 to 4 millimeters per year over recent decades, consistent with regional trends across South Florida (NOAA Sea Level Trends). Over a 30-year mortgage, that is 9 to 12 centimeters of additional mean sea level.
For direct oceanfront and low-elevation canal-front properties, that trend affects long-term flood insurance pricing, FEMA flood map reclassification risk, and the future buyer pool.
Buyers taking a 5- to 10-year investment horizon in Fort Lauderdale waterfront real estate are not immediately affected by sea-level trends in the way a 30-year owner-occupant would be.
But buyers who plan to hold a waterfront property long-term should account for the likelihood that flood insurance costs will rise and that FEMA may reclassify adjacent parcels to higher-hazard designations in future map revisions.
Elevation certificates that show favorable elevation above base flood level today provide more buffer against those reclassifications.
For buyers weighing whether sea-level risk changes the investment calculus on Fort Lauderdale waterfront property, waterfront living affects property value by reflecting how the market has historically priced that risk against the sustained demand premium for water access.
What Storm-Resilient Features Should Fort Lauderdale Buyers Look For?
Fort Lauderdale’s building codes require impact-resistant windows and doors for new construction and major renovations following post-Andrew code revisions in 1994 and further updates after the 2004-2005 hurricane seasons.
Homes with these features in place produce better wind mitigation inspection reports, which directly reduce homeowners insurance premiums.
Buyers evaluating older homes that predate these requirements should budget for window and door upgrades as a near-term capital expenditure.
Structural Features That Reduce Insurance and Risk
Roof construction is the highest-impact variable in Fort Lauderdale’s insurance market. Hip roofs (four-sloping sides) perform better in wind events than gable roofs and qualify for greater wind mitigation discounts.
Roof-to-wall connections, particularly hurricane clips and straps visible in the attic, are documented in wind mitigation inspections and affect premium calculations. A roof over 20 years old may trigger coverage restrictions regardless of visible condition.
Homes with whole-home generators, elevated mechanical systems, and sealed crawl spaces or slab foundations perform better in flood events. These features are increasingly standard in new construction and renovations in Fort Lauderdale’s waterfront neighborhoods.
What to Request Before Closing
Four documents every Fort Lauderdale buyer should obtain during the inspection period: the elevation certificate, the most recent wind mitigation inspection report, the four-point inspection report (required by most Florida insurers for homes over 20 years old), and the CLUE report showing the property’s prior insurance claims history.
A property with multiple prior water damage claims is not uninsurable, but it will cost more and may have lender restrictions on coverage types.
For a full breakdown of what these inspections reveal and what the numbers mean for total carrying costs, see Hidden Costs of Buying a Waterfront Home in Fort Lauderdale.
What Does Fort Lauderdale Weather Mean for Home Insurance Costs?
Weather drives insurance costs in Fort Lauderdale more directly than in most U.S. markets. The combination of hurricane wind exposure, FEMA flood zone designations, and Florida’s tightened insurance market since 2022 often surprises buyers with the gap between the mortgage payment and the total monthly carrying cost.
Combined annual homeowners and flood insurance on a canal-front home in Fort Lauderdale typically runs $8,000 to $20,000. Intracoastal and oceanfront properties often exceed $30,000 annually.
Fort Lauderdale waterfront home insurance costs cover the full breakdown of insurance cost ranges by waterfront type, the factors that drive premiums up or down, and how to reduce costs through elevation certificates and wind mitigation inspections.
Buyers who obtain insurance quotes before submitting an offer are in a materially stronger negotiating position. A property with a poor insurance profile has a smaller pool of buyers. That is leverage.
Frequently Asked Questions
Does hurricane season affect home prices in Fort Lauderdale?
Hurricane season doesn’t consistently lower prices, but it does affect market pace. Some sellers price more aggressively from August through October to close before peak season activity.
Buyers already committed to Fort Lauderdale who move during this window sometimes find less competition and more room to negotiate than in the spring market.
What flood zone is Fort Lauderdale in?
Fort Lauderdale has multiple flood zone designations. Most waterfront properties fall in Zone AE or VE, which require flood insurance for federally backed mortgages.
Inland and higher-elevation properties may fall in Zone X, which carries no mandatory flood insurance requirement. Verify the specific designation for any address at msc.fema.gov before making an offer.
How does Fort Lauderdale weather affect homeowners insurance?
Fort Lauderdale’s hurricane exposure and FEMA flood zone designations produce some of the highest combined insurance costs in the continental U.S. for waterfront properties.
Roof age, construction type, impact window installation, elevation certificate rating, and prior claims history are the main variables. Buyers should obtain a full insurance quote during the inspection period, not after closing.
Is it safe to buy in Fort Lauderdale given sea-level rise?
Fort Lauderdale’s waterfront market has sustained strong demand and price appreciation despite documented sea-level rise trends. Buyers with a 5- to 10-year horizon face minimal near-term impact.
Long-term owners should monitor FEMA flood map revisions and insurance cost trajectories. Elevated properties with strong elevation certificates are better positioned for long-term insurability.
What is the best time of year to buy in Fort Lauderdale?
There is no universally best time, but the late-summer and early-fall window during peak hurricane season often has less buyer competition and more motivated sellers.
The spring market (February through April) has more inventory and more competition. Buyers focused on value rather than selection often do better in the off-peak window.
Fort Lauderdale’s Weather Is Not a Surprise. Paying Too Much Because of It Is.
Most buyers find out what hurricane season, flood zones, and insurance costs mean for their purchase after the offer is accepted.
The Dotoli Group walks every buyer through climate-related cost factors before an offer goes in: insurance estimates, flood zone review, elevation certificate analysis, and neighborhood drainage context. Ranked #1 Fort Lauderdale Large Team, RealTrends Verified 2026.
Start the conversation before you start the search. Know your full cost before you fall in love with a house.